Market Briefing • Indian Equity Outlook
Nifty 50 Recovery: Is 22,000 the Bottom?
By 360 Research Desk • October 21, 2026 • 8 min read
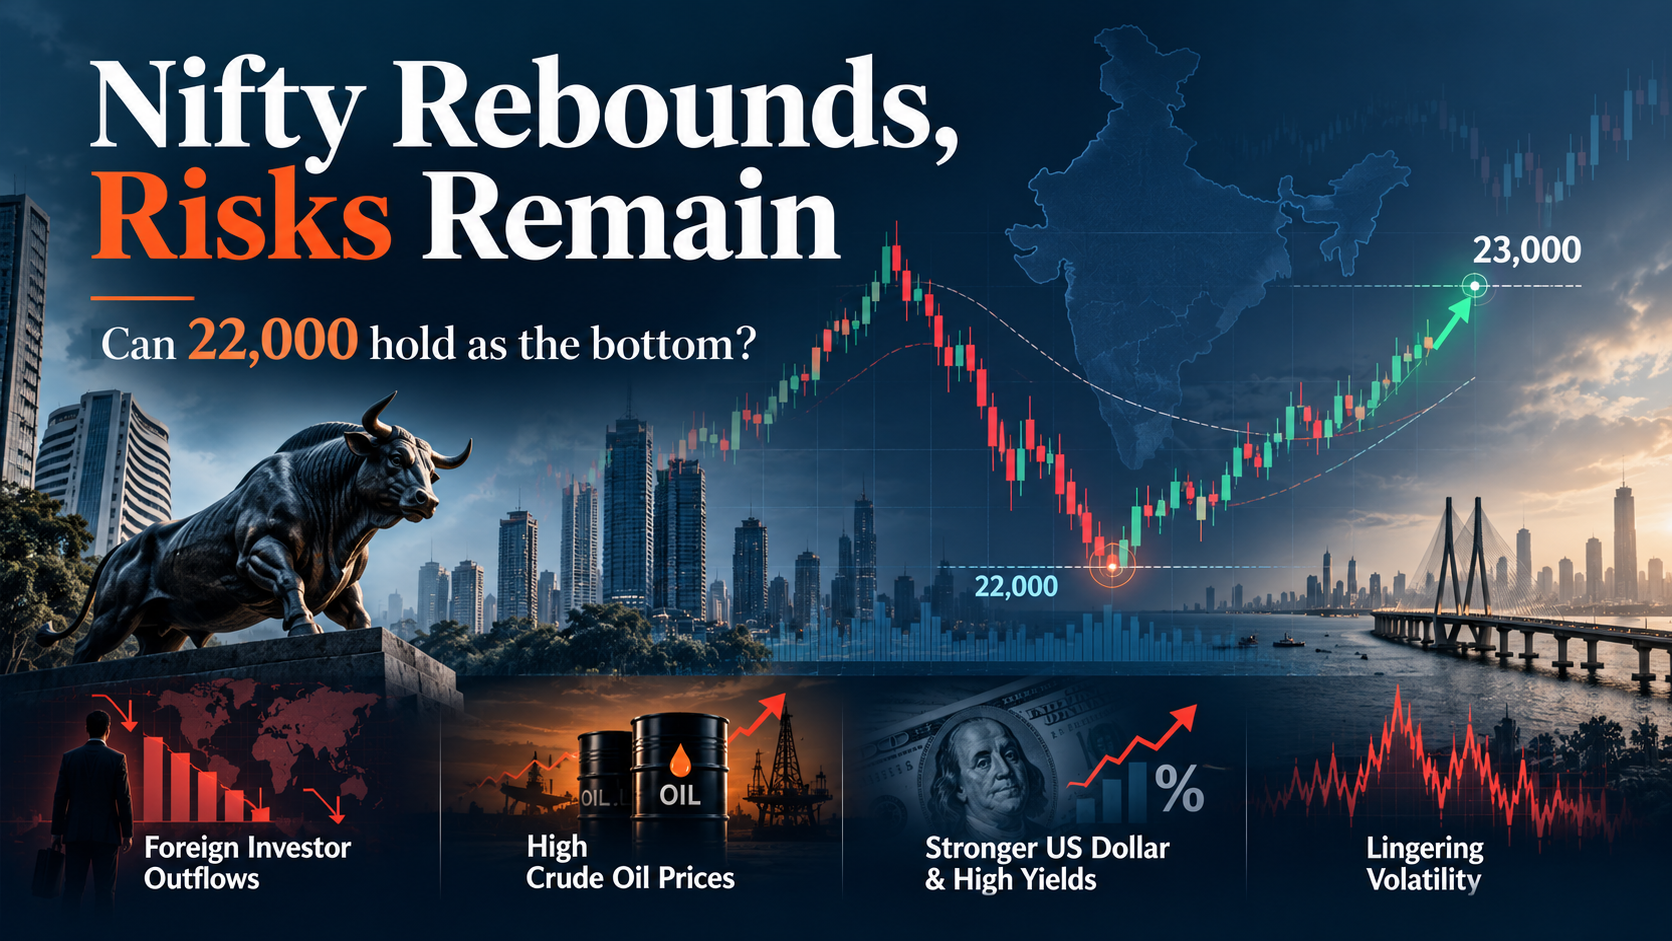
After a correction of nearly 9%, the Nifty 50 has rebounded towards 23,000. Yet continued FII outflows, elevated crude oil prices and earnings risks mean the recovery is not necessarily a broad-based, sustainable uptrend.
1. The market has bounced, but the worries have not disappeared
Over the past three months, the Nifty 50 has experienced a correction of nearly 9%, followed by a sharp recovery towards the 23,000 mark. The rebound has brought some relief to investors, but it has not yet resolved the concerns weighing on Indian equities.
The recent recovery has been led by heavyweight stocks in information technology, Reliance Industries and major private-sector banks such as HDFC Bank and ICICI Bank. Because these stocks carry substantial weight in the benchmark, even a recovery concentrated in a handful of large companies can lift the Nifty meaningfully.
But a rising index does not necessarily mean the entire market has recovered. Investors must distinguish between a relief rally driven by heavyweight stocks and a sustainable, broad-based market uptrend.
The fundamental question is whether earnings growth, liquidity and valuations can now support the recovery—or whether external risks will trigger another bout of volatility.
2. FII selling remains the biggest overhang
One of the most important concerns is the continued selling by foreign portfolio investors (FPIs). According to recent market reports, FPIs withdrew approximately ₹52,100 crore from Indian equities during October through the reported period, following substantial outflows in preceding periods.
This selling reflects several global pressures:
- Elevated US bond yields, making dollar-denominated assets more attractive.
- A stronger US dollar and pressure on the Indian rupee.
- Geopolitical uncertainty encouraging investors to reduce exposure to emerging markets.
- Concerns that higher energy prices could weaken India’s growth and corporate profitability.
The direction of FII flows will therefore remain an important signal for the market.
3. High crude oil prices: India’s macroeconomic vulnerability
India imports a substantial share of its crude oil requirements. When oil prices rise sharply, the consequences extend well beyond the energy sector.
Higher crude prices can:
- Increase the import bill and put pressure on the current account.
- Weaken the rupee and raise imported inflation.
- Increase fuel, logistics, packaging and raw-material costs for companies.
- Reduce disposable income and potentially weaken consumer demand.
- Complicate monetary policy if inflationary pressure persists.
For Indian companies, the impact varies by sector. Oil marketing companies, airlines, paints, chemicals, logistics and other fuel-sensitive businesses may face pressure, while companies with pricing power or lower energy intensity may be better positioned.
The concern for equity investors is that higher input costs can reduce earnings even when revenue growth remains healthy.
4. Freight costs and supply-chain uncertainty
Geopolitical disruptions can raise shipping insurance premiums, freight rates and delivery times. Companies dependent on imported components, specialty chemicals, crude derivatives or overseas markets may experience a double impact from higher freight costs and currency depreciation.
The immediate effect is often felt through working capital: companies need to hold more inventory, fund longer transit periods and absorb higher procurement costs.
This makes the next two quarters of corporate earnings particularly important. Investors should monitor gross margins, inventory levels, debtor days and management commentary on pricing power.
5. Domestic political uncertainty adds another layer of risk
Political protests, policy disagreements and uncertainty around government priorities can weigh on investor confidence, particularly when global conditions are already fragile.
The market impact depends on whether these developments cause actual disruption to economic activity, investment decisions, policy execution or public spending.
For now, geopolitical and macroeconomic risks are interacting with domestic uncertainty, making sentiment more fragile than the index rebound might suggest.
6. Historical perspective: corrections are normal, but recoveries are not always immediate
History offers two useful lessons: markets can recover sharply during periods of pessimism, but investors should not assume every correction has reached its bottom.
| Market episode | Nifty 50 peak-to-trough decline | Approximate recovery lesson |
|---|---|---|
| Global financial crisis, 2008 | Around 60% | Recovery to the prior high took several years |
| 2015–16 correction | Around 23% | Recovery to the prior high took roughly two years |
| COVID-19 shock, 2020 | Around 38% | The rebound was unusually rapid after policy support and economic reopening |
| 2022 correction | Around 17% | The market recovered as inflation and global risk concerns moderated |
7. Valuations: the correction has improved the risk-reward equation
Recent data put the Nifty 50’s price-to-earnings ratio at approximately 19.8 times on 15 October 2026, compared with a reported five-year average of 21.9 times and a ten-year average of 24.8 times.
That represents a meaningful reset in the index multiple.
| Valuation measure | Latest reported figure |
|---|---|
| Nifty 50 P/E | 19.8x |
| Five-year average P/E | 21.9x |
| Ten-year average P/E | 24.8x |
| Latest P/E versus five-year average | About 10% lower |
However, historical averages should not be treated as a guaranteed fair value. If earnings estimates decline, a lower P/E may be justified. Likewise, higher bond yields can cause investors to demand a lower valuation multiple for equities.
The biggest risk is that higher costs and slower demand reduce earnings estimates just as investors are hoping for a valuation rebound.
8. Is 22,000 the bottom for Nifty?
Our working view is that 22,000 could act as a strong support zone and may represent the likely bottom in the base-case scenario, provided the global situation does not deteriorate materially.
Three factors support this view:
- Valuation support: The Nifty’s P/E has moved below its recent historical averages, reducing some of the excess valuation premium.
- A meaningful correction has already occurred: The market has experienced a significant drawdown, and some pessimism is reflected in prices.
- Domestic liquidity remains a cushion: Institutional buying at home can absorb part of the foreign selling pressure.
There are, however, important conditions. A sustained fall in crude oil prices, stabilisation in the rupee, easing FII outflows and resilient corporate earnings would strengthen the case for 22,000 holding.
Conversely, a prolonged geopolitical shock, further crude escalation, a sharp downgrade in earnings or an acceleration in foreign selling could push the index below this level.
The latest completed session also serves as a reminder that the recovery is fragile: on 19 October, the Nifty closed at 22,888.95 after falling 1.11%, with higher crude prices and weakness in private banks weighing on the market.
Conclusion: A cautious bottoming process, not an all-clear signal
The recovery towards 23,000 should be viewed as an encouraging development, but not definitive proof that the correction is over. Large-cap IT, Reliance and banking stocks can support the benchmark, yet a durable recovery will require broader participation, improving earnings visibility and stabilising foreign flows.
For investors, the strategy should be to avoid excessive leverage, maintain adequate liquidity and accumulate fundamentally strong businesses in a staggered manner rather than attempting to predict the exact bottom.
Our base-case view is that 22,000 is likely to be the bottom for Nifty in this correction, supported by improved valuations and domestic liquidity. This is a conditional market view, not a certainty: global shocks and earnings downgrades could invalidate it.
The next phase will depend on whether improving valuations are followed by improving fundamentals. Until then, selective investing and disciplined risk management remain more important than chasing every relief rally.